30. 9. 2026
General Financial Directorate clarifies property sale exemption for own housing needs

News & blog
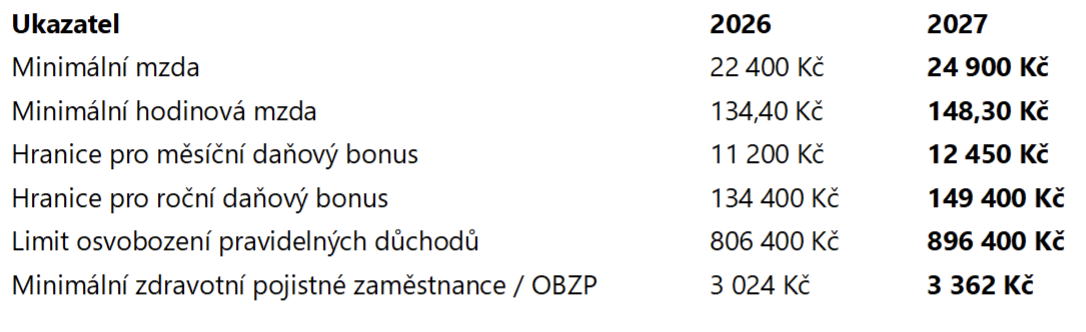
From 1 January 2027, the minimum wage will increase from CZK 22,400 to CZK 24,900 per month. The minimum hourly wage for a standard 40-hour working week will amount to CZK 148.30. However, the increase in the minimum wage will not affect employers’ payroll costs alone. Its level also influences certain thresholds relating to personal income tax and health insurance.
One area directly linked to the minimum wage is eligibility for the child tax bonus for a dependent child. The thresholds below do not represent the amount of the tax bonus itself, but rather the minimum income a taxpayer must earn in order to qualify for its payment. To claim the annual tax bonus, a taxpayer must earn income from employment or self-employment amounting to at least six times the minimum wage. In 2027, the minimum required annual income will therefore increase to CZK 149,400.
For employees, the threshold for receiving the monthly tax bonus will also increase. This threshold corresponds to one half of the minimum wage. From 2027, an employee will therefore need to earn at least CZK 12,450 in the relevant month in order to receive the monthly tax bonus. The actual amount of the tax allowance for dependent children will not change as a result of the increase in the minimum wage.
The minimum wage also affects the threshold for the exemption of regularly paid pensions and retirement benefits from income tax. Their total annual amount is exempt from tax up to 36 times the minimum wage applicable as of 1 January of the relevant year. In 2027, this threshold will therefore amount to CZK 896,400 per year. Compared with 2026, when the threshold amounts to CZK 806,400, the tax-exempt limit will therefore increase by CZK 90,000.
The minimum wage also represents the minimum assessment base for employees’ health insurance contributions, unless one of the statutory exemptions applies. With a minimum wage of CZK 24,900, the minimum health insurance contribution in 2027 will amount to approximately CZK 3,362 per month.
This change may be particularly relevant for employees with low incomes or part-time employment. If their actual assessment base does not reach the level of the minimum wage, they may be required to pay an additional health insurance contribution up to the minimum assessment base. Exemptions apply, for example, to certain categories of individuals whose health insurance is also paid by the state.
The increase in the minimum wage will also directly affect persons without taxable income (OBZP), whose health insurance assessment base is equal to the minimum wage. Their monthly health insurance contribution will therefore increase from CZK 3,024 in 2026 to CZK 3,362 in 2027.
Not all tax and contribution thresholds are linked to the minimum wage. For example, the minimum health insurance advances for self-employed individuals are calculated on the basis of the average wage, not the minimum wage. An increase in the minimum wage therefore does not directly determine their amount. We recommend that employers reflect these changes in their payroll systems and contribution calculations from January 2027, particularly in the case of employees with lower incomes and part-time working arrangements.
Do you need to prepare for changes in wages, contributions or tax thresholds from 2027? Contact us and we will help you correctly set up your payroll processes and related obligations.
Author: Jaroslava Ševčíková - Tax Assistant